Boulder Creek Homeowners Insurance: 2026 FAIR Plan Hike
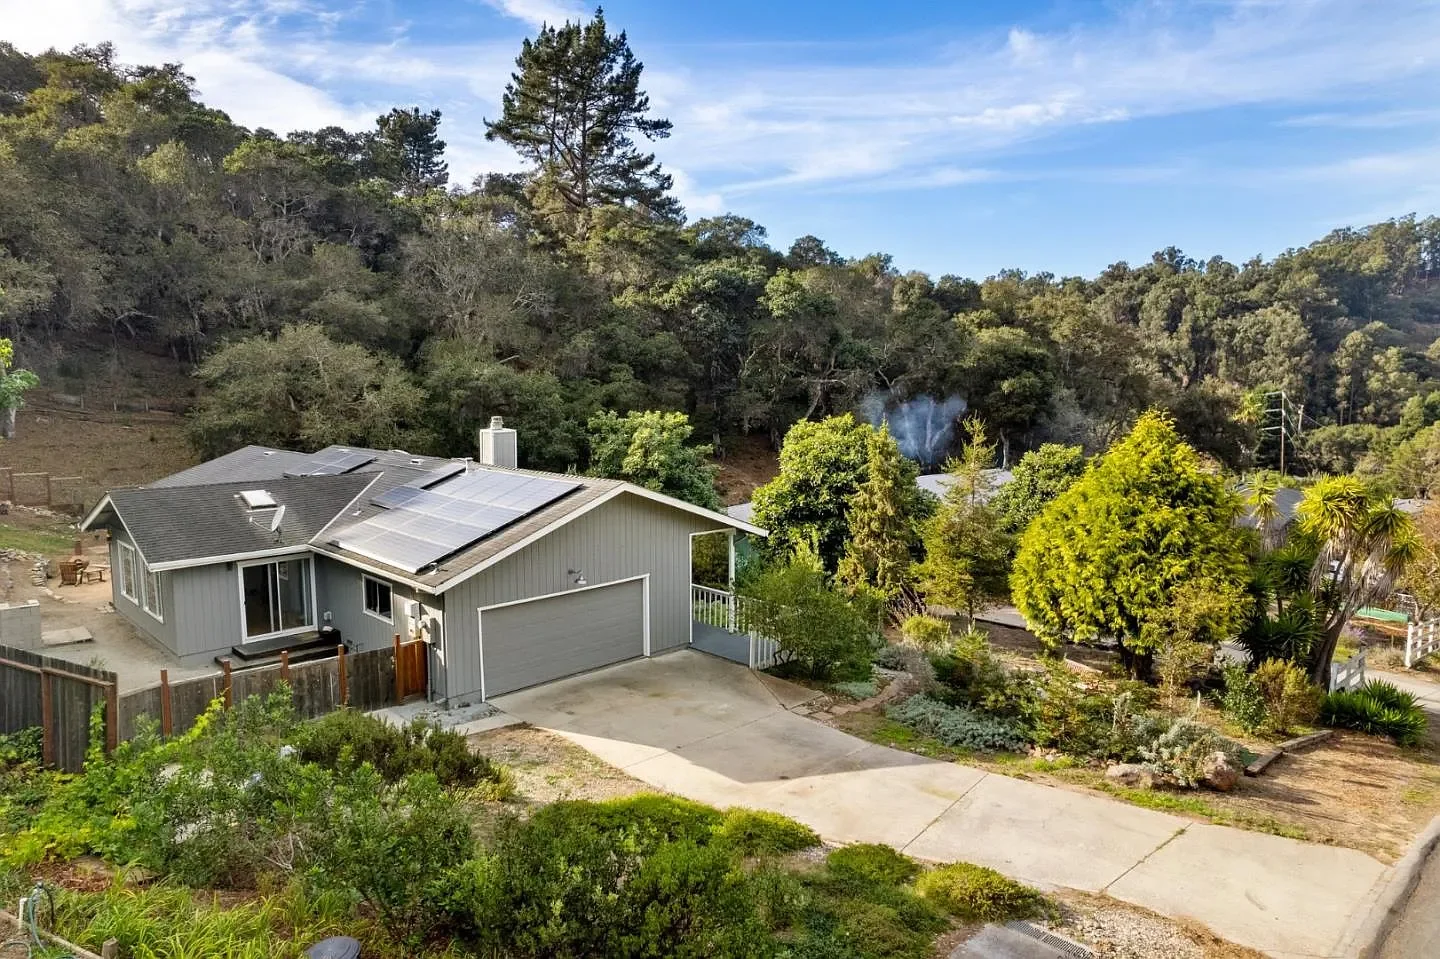
If you own a home in Boulder Creek, you've probably already had the call: the one where your agent or broker tells you your policy isn't renewing, and the replacement quote is two or three times what you were paying. That call is about to get more common. The California FAIR Plan, the insurer of last resort for the state's highest fire-risk properties, is raising rates by an average of 29.1 percent starting October 15, 2026, and Boulder Creek, sitting closer to the CZU burn scar than almost anywhere else in the mountains, is going to feel it more than most.
What's Actually Changing on October 15
The FAIR Plan asked state regulators for a 35.8 percent increase and got approved for 29.1 percent instead, which sounds like a win until you run the math on a policy that was already costing $700 to $1,200 a month for a lot of Boulder Creek homeowners. That's up from the $100 to $200 a month insurance used to run before wildfire risk got repriced across California. The increase isn't arbitrary. The FAIR Plan's total exposure has grown to $768 billion as of June 2026, up 250 percent since September 2022, and homes near the 2020 burn footprint sit squarely inside the zones driving that number, according to KQED's coverage of the rate hike.
Why Boulder Creek Feels This More Than Felton or Ben Lomond
Nearly every home up here ends up on the FAIR Plan at some point, and the closer you sit to the burn footprint, the fewer standard carriers are willing to write you a policy at all. Some carriers are starting to come back and write house by house again, which is genuinely good news, but it usually comes with conditions: a recent defensible space inspection, a newer roof, and sometimes proof of Zone 0 compliance before they'll quote you anything.
Last year, roughly 15,000 Santa Cruz County homeowners faced non-renewal, and State Farm alone dropped about 4,300 county policyholders. That's a countywide number, not a Boulder Creek-only one, but this canyon absorbed more than its share.
There's a piece of this that gives me real hope, too. Volunteers have been out at Big Basin Redwoods State Park this September clearing fuels, thinning the kind of undergrowth that let the CZU fire move as fast as it did back in 2020. It won't change anyone's premium overnight, but insurers do pay attention to community-level mitigation over time, and it's the kind of quiet, unglamorous work that makes Boulder Creek a harder sell for pessimists and an easier one for people who've actually spent time here.
What This Means If You're Buying Here
I tell every buyer looking in Boulder Creek the same thing: get an actual insurance quote before you're in contract, not after. A house that looks like a deal on paper turns into a very different number once you add $10,000 to $14,000 a year in fire coverage on top of the mortgage. That's not a reason to walk away from Boulder Creek. It's a reason to walk in with your eyes open, and a number in hand before you fall in love with the place.
Questions worth asking before you write an offer
Is the home in a Very High Fire Hazard Severity Zone, and has it had a Cal Fire defensible space inspection recently?
What's the roof age and material, and how much non-combustible clearance exists within 5 feet of the structure? That's the Zone 0 standard insurers are already asking about informally, even before it's formally enforced.
Has the current owner been on the FAIR Plan, or have they had a standard carrier quote in the last year?
What did the seller actually pay last year, not what a listing's "estimated insurance" line suggests?
What This Means If You're Selling Here
If you've done the defensible space work, the roof replacement, the ember-resistant vents, say so specifically in your listing. Buyers are more afraid of an unknown insurance number than a known one, and specifics calm that fear faster than anything else does. "New Class A roof in 2024, cleared to Zone 0 standards, current FAIR Plan policy $9,200 a year" tells a buyer more than any version of "move-in ready" ever could.
This isn't a reason to avoid Boulder Creek. It's a canyon full of people who chose it on purpose, insurance costs and all. But if you're thinking about buying or selling up here, let's talk through the real numbers before they become a surprise at the closing table. I'm always happy to walk through it with you.
Insurance rates, coverage rules, and Zone 0 regulations change quickly. Verify current pricing and requirements with a licensed insurance broker before making a purchase or listing decision.